
Keywords: Inventory optimization, Stock control, inventory tracking, Supply chain, management
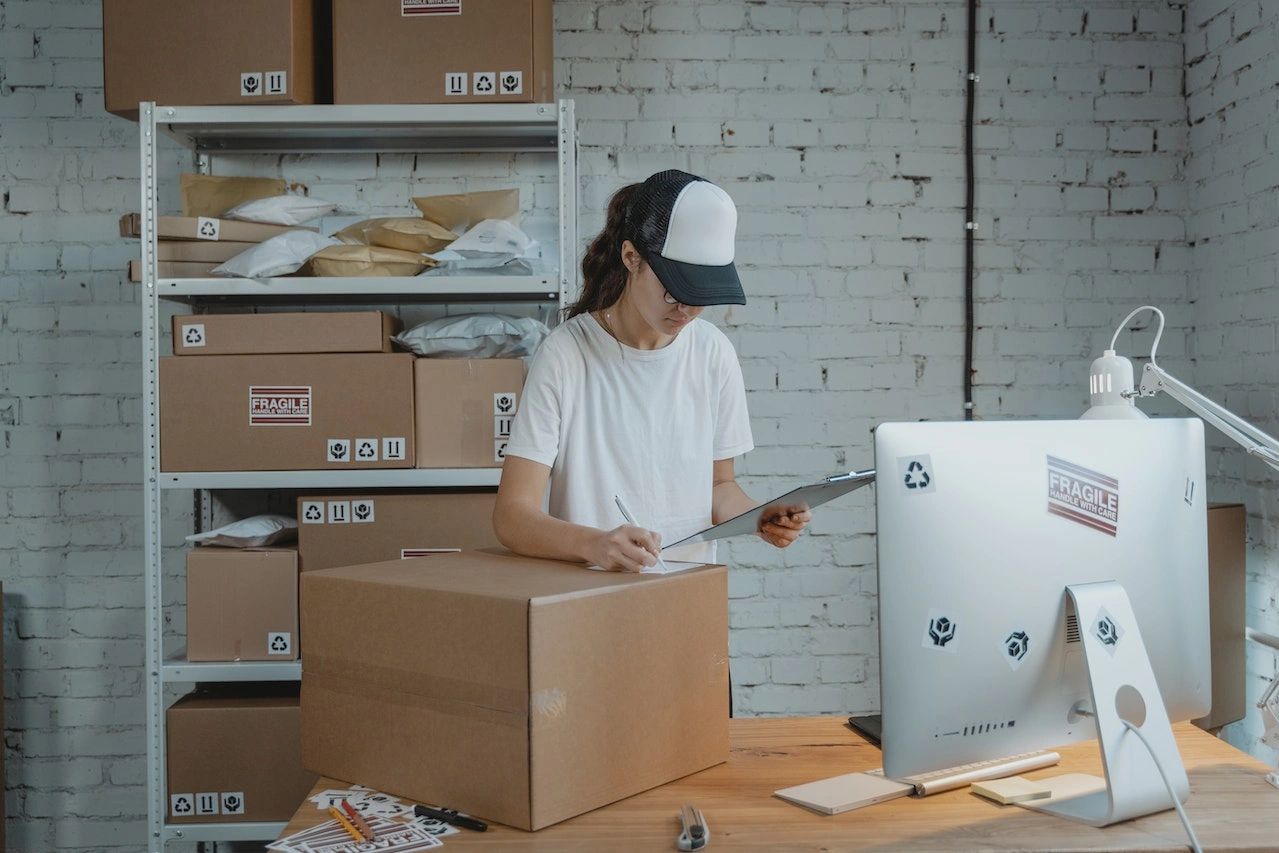
Written By: Sultan Coker Photo by: Tima Miroshnichenko
Table of Contents:
II. Importance of Effective Inventory Management
III. Determining Optimal Inventory Levels
IV. Using Inventory Management Software
V. Implementing a First-in, First-out (FIFO) Inventory System
VI. Regularly Reviewing Inventory Turnover
VII. Using Just-in-Time (JIT) Inventory Management
VIII. Implementing an Inventory Tracking System
IX. Challenges in Inventory Management
I. Introduction
Effective inventory management is essential for the success of small and mid-sized businesses. Managing inventory efficiently can be challenging, but it is crucial for businesses looking to remain competitive in their industries. Inefficient inventory management can lead to increased costs, lost sales, and disappointed customers. On the other hand, effective inventory management can help businesses reduce costs, improve customer service, and increase profitability.
II. Importance of Effective Inventory Management
Inventory management is critical for small and mid-sized businesses because it directly affects their bottom line. Effective inventory management helps businesses ensure they have the right products in stock, avoid stockouts, reduce waste and spoilage, and improve their bottom line. By determining optimal inventory levels, using inventory management software, implementing a FIFO inventory system, regularly reviewing inventory turnover, using JIT inventory management, and implementing an inventory tracking system, small and mid-sized businesses can reduce costs, improve customer service, and increase profitability.
III. Determining Optimal Inventory Levels
Small and mid-sized businesses need to determine the optimal inventory levels for their business. This involves finding a balance between carrying enough inventory to meet customer demand while minimizing carrying costs. By setting optimal inventory levels, businesses can avoid overstocking or understocking, which can lead to lost sales or increased carrying costs. One way to determine optimal inventory levels is to use historical sales data to forecast future demand and determine how much inventory is needed to meet customer demand.
For example, a small boutique may determine that they need to have 100 dresses in stock to meet demand. If a business carries too much inventory, they risk tying up capital and incurring carrying costs. If a business carries too little inventory, they risk losing sales and disappointing customers. Inventory management is an ongoing process, and businesses should regularly review their inventory levels to ensure they are meeting customer demand while minimizing carrying costs.
IV. Using Inventory Management Software
Using inventory management software can help small and mid-sized businesses manage inventory more efficiently. Inventory management software can automate many inventory-related tasks, such as tracking inventory levels, ordering new inventory, and forecasting demand. This can help businesses reduce errors, save time, and improve accuracy. For example, a small electronics retailer may use inventory management software to track inventory levels and reorder products automatically when the inventory level falls below a certain threshold. This can help businesses reduce errors, save time, and improve accuracy. Inventory management software can also provide businesses with valuable insights into their inventory, such as which products are selling well and which products are not. This information can help businesses make informed decisions about inventory levels and product offerings.
V. Implementing a First-in, First-out (FIFO) Inventory System
Implementing a first-in, first-out (FIFO) inventory system is another practical tip that small and mid-sized businesses can use to manage their inventory effectively. A FIFO inventory system is a method of inventory management where the oldest inventory is sold or used first, ensuring that inventory does not expire or become outdated. For businesses dealing with perishable goods, such as food or pharmaceuticals, implementing a FIFO inventory system is crucial to ensure the quality and safety of their products.
However, even businesses that deal with non-perishable goods can benefit from using a FIFO system. By selling or using the oldest inventory first, businesses can avoid the risk of inventory becoming obsolete or outdated, which can lead to lost sales and wasted resources. A small grocery store, for example, may implement a FIFO inventory system for perishable goods such as dairy products. This means that the oldest inventory is sold or used first, ensuring that inventory does not expire or become outdated. If a business does not use a FIFO system, they may risk having inventory expire or become outdated, resulting in lost sales and wasted resources. Implementing a FIFO system is relatively easy, and businesses can do it manually using spreadsheets or other inventory tracking tools. However, businesses can also use inventory management software that has FIFO functionality built-in. This can help automate the process and reduce the risk of errors.
VI. Regularly Review Inventory Turnover
Regularly reviewing inventory turnover is another practical tip that small and mid-sized businesses can use to manage their inventory effectively. Inventory turnover measures how quickly a business sells its inventory and can help business owners identify slow-moving inventory. For example, a small hardware store may review inventory turnover every month. Slow-moving inventory can tie up capital and lead to increased carrying costs. By regularly reviewing inventory turnover, businesses can identify slow-moving inventory and take action to reduce carrying costs or increase sales.
To calculate inventory turnover, divide the cost of goods sold by the average inventory value. The resulting number represents how many times a business has sold and replaced its inventory in a given period. A high inventory turnover indicates that a business is selling its inventory quickly, while a low inventory turnover indicates that a business is holding onto its inventory for longer periods. By regularly reviewing inventory turnover, businesses can make informed decisions about inventory levels and adjust their inventory management strategies as needed to meet changing customer demand and market conditions.
VII. Using Just-in-Time (JIT) Inventory Management
Another effective method for managing inventory is using just-in-time (JIT) inventory management. This method is commonly used by businesses to reduce inventory levels and minimize carrying costs. JIT inventory management involves ordering inventory only when it is needed, reducing the need for large inventory levels.
For example, a small manufacturing company may use JIT inventory management to order materials only when they are needed in the production process. This can help businesses reduce waste and improve cash flow. By using JIT inventory management, businesses can reduce the need for large inventory levels and minimize carrying costs.
However, implementing JIT inventory management requires a high level of coordination and communication with suppliers. Businesses must ensure that their suppliers can deliver materials in a timely manner to avoid production delays. They also need to have a system in place to monitor inventory levels and reorder materials when needed. If not implemented properly, JIT inventory management can lead to stockouts and lost sales.
VIII. Implement an Inventory Tracking System
Implementing an inventory tracking system is another practical tip that small and mid-sized businesses can use to manage their inventory effectively. An inventory tracking system can help businesses keep track of inventory levels, track inventory movement, and identify potential issues such as theft or spoilage. For example, a small jewelry store may use a barcode system to track inventory movement. By scanning barcodes, the store can keep track of which items are in stock, which items have been sold, and which items are on order. This can help improve inventory accuracy, reduce errors, and identify potential issues before they become major problems. Inventory tracking systems can range from simple manual systems, such as spreadsheets, to more advanced software systems that can automate many inventory-related tasks. Businesses should choose an inventory tracking system that is appropriate for their size and complexity of operations.
IX. Challenges in Inventory Management
While effective inventory management is critical for small and mid-sized businesses, there are several challenges that businesses may face when managing inventory. One of the biggest challenges is forecasting demand accurately. Small businesses may not have access to the same data and resources as larger companies, making it difficult to predict demand with accuracy. This can lead to overstocking or understocking, both of which can result in lost sales and increased carrying costs. Another challenge is managing inventory turnover. Slow-moving inventory can tie up capital and lead to increased carrying costs, while fast-moving inventory can result in stockouts and lost sales. Finally, inventory management requires ongoing monitoring and adjustment. Businesses must regularly review their inventory levels and adjust their inventory management strategies as needed to meet changing customer demand and market conditions.
X. Conclusion
In conclusion, effective inventory management is critical for small and mid-sized businesses looking to remain competitive in their industries. By implementing the six practical tips discussed in this article, small and mid-sized businesses can manage their inventory more efficiently, reduce costs, improve customer service, and increase profitability.
To recap, the six tips are:
- Determine optimal inventory levels
- Use inventory management software
- Implement a first-in, first-out (FIFO) inventory system
- Regularly review inventory turnover
- Use just-in-time (JIT) inventory management
- Implement an inventory tracking system
While implementing these tips can help businesses improve their inventory management practices, it’s important to remember that inventory management is an ongoing process that requires monitoring and adjustment. By regularly reviewing inventory levels and adjusting inventory management strategies as needed, small and mid-sized businesses can continue to improve while building a solid foundation for growth and success.
In the end, businesses that prioritize effective inventory management will be better equipped to meet customer demand, reduce costs, and increase profitability, ultimately positioning themselves for long-term success.
Check out our Homepage